
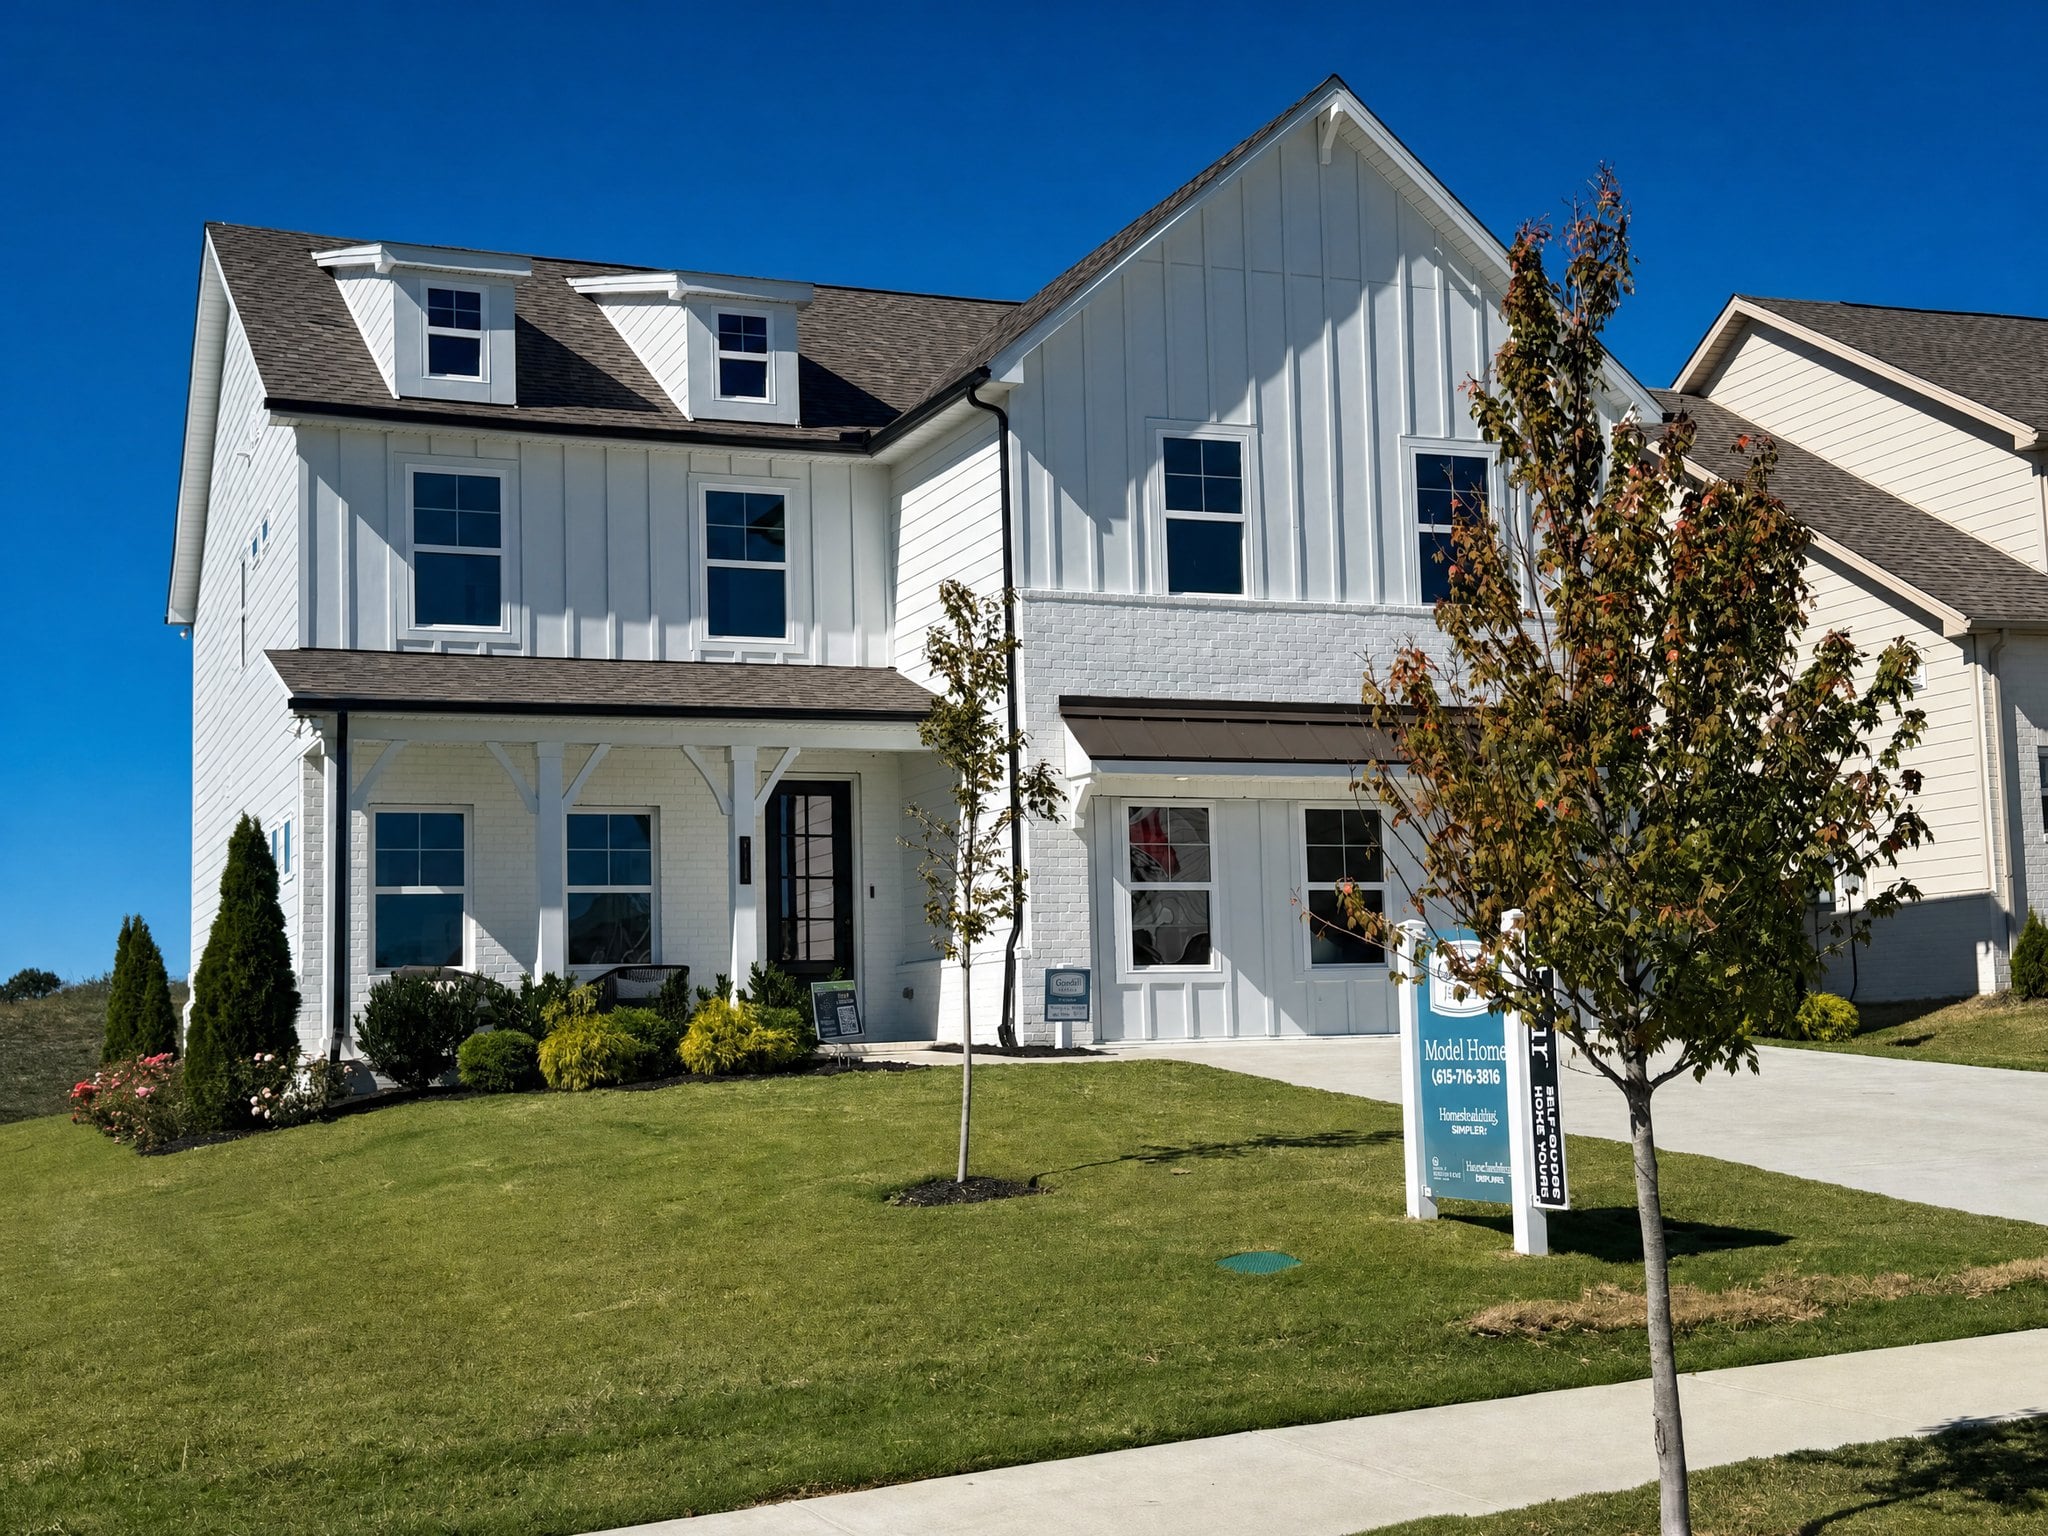
If you're selling a house in Spring Hill this fall, your toughest competition might not be the neighbor's listing. It's the model home a few miles away with a banner advertising a rate in the 5s and $15,000 toward closing costs. Buyers walk through your house on Saturday morning and a builder's model that afternoon, and they compare the two on monthly payment, not just price. You can win that comparison. You just have to know what the builder is offering and price and package your home with it in mind.
Quick answer (as of October 2026): In Spring Hill, a resale home competes with new construction on four things: price, the money the seller puts toward the buyer's costs, condition and timing. As of October 23, 2026, Spring Hill builders are advertising rate specials, closing cost credits, options money, price cuts and a three-month payment skip, and most of them require a lender the builder picks. A resale seller can offer a closing cost credit or a rate buydown that works with any lender, as long as it stays under the buyer's loan cap: 6% on FHA, 4% on VA, and 3% to 9% on conventional loans.
What are Spring Hill builders offering buyers right now?
These are the offers posted on each builder's own site as of October 23, 2026. They change weekly, and my Spring Hill builder incentives page carries the current list.
| Community and builder | County | What's advertised, as of October 23, 2026 | Conditions as printed |
|---|---|---|---|
| Arbor Valley, Goodall Homes | Maury | 5.49% rate (6.250% APR) on select homes. Up to $20,000 in options on to-be-built homes, plus $15,000 in closing costs | Goodall's approved lender and title company required. Incentives can't be combined. Limited time, no end date published |
| Harvest Point, D.R. Horton | Maury | Red Tag Event price cuts on finished homes, for example a home shown at $489,990, "was $565,215" | Ends November 1, 2026. No rate or lender condition published |
| August Park, Richmond American | Williamson | 4.999% FHA 30-year fixed (5.737% APR) | HomeAmerican Mortgage. Purchase agreement signed by November 15, 2026, close by December 31, 2026 |
| Barton Hills, Century Communities | Maury | "SKIP 3": no mortgage payment due for the first three months | Qualifying FHA loan with Inspire Home Loans, 640 minimum FICO score. Close on or before December 31, 2026 |
| Harvest Point townhomes, Regent Homes | Maury | 5.25% FHA 5/1 ARM financing | Homes closing by December 31, 2026. No APR or lender named on the banner |
Rates, APRs, buydowns and builder incentives on this page are published by the builder or lender named, were read on the date shown, and can change or end without notice. They are not an offer of credit from me or eXp Realty, and I am a licensed Realtor (TREC 369038), not a mortgage lender. Confirm the current terms, APR, eligibility and any lender requirement in writing with the builder or lender before you rely on them.
Two patterns stand out. Four of the five offers are on the Maury County side of Spring Hill; the one Williamson side offer is Richmond American's at August Park. And three of the five require a lender the builder picks: Goodall's approved lender, Richmond American's HomeAmerican Mortgage and Century's Inspire Home Loans. D.R. Horton publishes no lender condition on its price cuts, and Regent's banner names none. The full community list, with counties and price ranges, is on my Spring Hill new construction page.
How do I price a resale against builder incentives?
Start with your closest resale comps, then look at the new construction a buyer in your price range is touring that same week. Here's how the last 12 months of single-family closings with a Spring Hill mailing address break down by county side:
| Spring Hill single-family closings, 12 months through October 23, 2026 | Closed | Median sale price | Median price per sq ft | Median size (sq ft) |
|---|---|---|---|---|
| Williamson County side, all sales | 409 | $700,000 | $247 | 2,812 |
| Williamson County side, new construction | 102 | $908,900 | $273 | 3,304 |
| Maury County side, all sales | 527 | $496,500 | $231 | 2,282 |
| Maury County side, new construction | 164 | $508,625 | $220 | 2,282 |
The "all sales" rows include the new construction. Resale was the other 307 closings on the Williamson side and 363 on the Maury side.
Based on information from Realtracs® for the period October 23, 2025 through October 23, 2026.
What that means for your price depends on your side of the county line:
- On the Williamson County side, new construction was 25% of closings and sold well above the side's overall median, $908,900 against $700,000. Those new homes were also bigger (a median 3,304 square feet against 2,812) and sold for more per square foot ($273 against $247). On that side a typical resale is the lower-priced choice, and the builder's incentive is how a bigger new home tries to close the gap.
- On the Maury County side, new construction was 31% of closings and sold close to the side's overall median, $508,625 against $496,500, at the same median size of 2,282 square feet and a lower price per square foot ($220 against $231). On that side a buyer can tour new construction at about the price of the typical Spring Hill sale, so the builder's incentive is what tips the decision.
- Spring Hill homes went under contract quickly overall: a median 13 days on market on the Williamson County side and 19 on the Maury County side.
When a builder cuts a finished home, the way D.R. Horton's Red Tag homes at Harvest Point show it, that price becomes part of your buyer's comparison even if your house is nothing like it. A buyer who saw "$489,990, was $565,215" on Saturday has that number in their head when they see your list price.
Price to the resale comps, and then decide how to answer the builder's incentive: with price, with a concession, or with both. My home evaluation is the starting point for the first part.
Should I offer a concession or a rate buydown instead of cutting my price?
Often, yes. A builder's rate special works on the buyer's monthly payment, and you can answer it the same way the builder does.
A seller concession is money you agree to put toward the buyer's closing costs, prepaids or a rate buydown. A 2-1 buydown, for example, lowers the buyer's rate 2 points the first year and 1 point the second. My buydown calculator puts a buydown next to a price cut of the same dollars, so you can see which one moves a buyer's payment more.
Two rules apply to you and the builder alike. The buyer's loan caps what a seller can contribute: 6% of the price on FHA and USDA, 4% on VA, and 3%, 6% or 9% on conventional depending on the down payment. My seller concession limits page has the details. And a builder's incentive counts against those same caps, so the builder can't outspend the loan rules either.
A resale has one edge here. Your concession works with whatever lender the buyer already likes. Most of the builder offers above require a lender the builder picks. Some buyers don't want to switch lenders, and some can't because of where they're already approved.
How much Spring Hill sellers are giving in concessions depends on the price range and the subdivision, so I look at the concessions paid in your own comps when we price your home.
My home sale calculator shows what a concession does to what you walk away with, next to a price cut.
What do buyers compare between my home and a new build?
| What buyers compare | What the builder has | What you have |
|---|---|---|
| Monthly payment | A rate special, usually through its own lender | A concession or buydown that works with any lender |
| Cash to close | Closing cost credits, options money | A closing cost credit, within the loan's cap |
| Move-in date | A quick move-in date, or months out on a to-be-built home | A closing date you negotiate |
| What comes with the house | Depends on the builder. In early October 2026, one Goodall listing in Columbia advertised a fridge and blinds as part of its incentive | Whatever's already in the home: window coverings, appliances, a finished yard, a fence if you have one |
| Property tax | Depends on the county. 2026 combined city and county rate is $2.009 per $100 of assessed value on the Williamson side and $2.108 on the Maury side | Same rule. Your county side is the same tax your buyer pays |
Property tax figures are the county and city rates published for the year shown and are for planning only. Your actual bill depends on the assessed value, any exemptions and the city or district the home sits in. Confirm with the county assessor or trustee and your tax professional before you rely on a number.
The tax detail is on my Spring Hill property taxes page. If your house is on the Williamson side and most of the builder offers your buyer is touring are on the Maury side, that's a comparison worth spelling out in your listing.
Does condition matter more when I'm up against new construction?
Yes, because the comparison is with a house no one has lived in. A buyer standing in a builder's model isn't thinking about worn carpet or a tired roof. The repairs a buyer finds in your home get compared to zero.
What I'd look at before listing:
- Fix the items an inspector is sure to write up, so they don't turn into a repair negotiation later.
- Paint, carpet and lighting where they're dated.
- Have the age and service records for the roof, HVAC and water heater on hand. A new build comes with a builder warranty, and your paperwork is the answer to that.
When is the best time to sell against builder incentives?
Builder offers come with deadlines, and those deadlines are real. As of October 23, 2026, D.R. Horton's Red Tag Event ends November 1, Richmond American's August Park rate needs a purchase agreement signed by November 15, and three of the offers above (Richmond American, Century and Regent) require closing by December 31, 2026. When a buyer misses a builder's window, or needs a closing date the builder's terms don't allow, a resale that's already on the market picks them up.
Two timing points I'd plan around:
- Watch the builder deadlines in your price range. My incentives page updates them every week.
- A buyer who needs to close after a builder's close-by date, or sooner than a to-be-built home will be ready, is a buyer you can serve and the builder can't.
Spring Hill homes have been selling close to list price. Over the last 12 months the median single-family sale closed at 99.69% of list price on the Williamson County side and 99.98% on the Maury County side, and new construction closed at a median 100% of list on both sides.
Based on information from Realtracs® for the period October 23, 2025 through October 23, 2026.
Before you list, I'll pull the resale and new construction homes for sale in your price range on your side of the county line that week, because those homes are your real competition.
If you're selling in Spring Hill, the seller hub for Spring Hill has the rest of the process.
I'll put your house next to the new construction your buyer will tour and show you what it takes to win the comparison. DM me, text me or call 615-392-1186.
Frequently asked questions
Can a resale home compete with new construction in Spring Hill?
Yes. A resale competes on price, concessions, condition and timing. As of October 23, 2026, most Spring Hill builder offers require a lender the builder picks, while a resale seller's concession works with any lender, within the loan's cap.
Should I lower my price or offer a concession when builders are running incentives?
It depends on what moves the buyer's payment. A rate buydown funded by a seller concession can lower a monthly payment more than a price cut of the same dollars. My buydown calculator shows the two side by side.
How much can a seller contribute toward a buyer's costs in Tennessee?
It depends on the buyer's loan: 6% of the price on FHA and USDA, 4% on VA, and 3%, 6% or 9% on conventional loans depending on the down payment. Builder incentives count against the same caps.
What incentives are Spring Hill builders offering?
As of October 23, 2026: rate specials such as Goodall's 5.49% (6.250% APR) on select homes at Arbor Valley, Richmond American's 4.999% FHA (5.737% APR) at August Park and Regent's 5.25% FHA 5/1 ARM, closing cost credits and options money from Goodall, D.R. Horton's Red Tag price cuts at Harvest Point, and Century's three-month payment skip at Barton Hills. Most require a lender the builder picks.
Do builder incentives require using the builder's lender?
As of October 23, 2026, most Spring Hill offers do. Goodall requires its approved lender and title company, Richmond American names HomeAmerican Mortgage and Century names Inspire Home Loans. D.R. Horton's price cuts and Regent's banner name no lender.
Does it matter which county my Spring Hill home is in when I sell?
Yes. The county sets the property tax rate your buyer will pay and the school district. For 2026, the combined city and county rate inside Spring Hill is $2.009 per $100 of assessed value on the Williamson side and $2.108 on the Maury side.
How much of the Spring Hill market is new construction?
Over the 12 months through October 23, 2026, new construction was 25% of single-family closings with a Spring Hill mailing address on the Williamson County side (102 of 409) and 31% on the Maury County side (164 of 527). The Williamson side's new construction median was $908,900 against $700,000 for all sales there, and the Maury side's was $508,625 against $496,500. Based on information from Realtracs® for the period October 23, 2025 through October 23, 2026.
When is the best time to list against new construction?
Around the builder deadlines. As of October 23, 2026, D.R. Horton's Red Tag Event ends November 1, Richmond American's August Park rate needs a purchase agreement signed by November 15, and three Spring Hill offers require closing by December 31, 2026. Buyers who miss a builder window, or need a different closing date, are buyers a resale can serve.
Rates, APRs, buydowns and builder incentives on this page are published by the builder or lender named, were read on the date shown, and can change or end without notice. They are not an offer of credit from me or eXp Realty, and I am a licensed Realtor (TREC 369038), not a mortgage lender. Confirm the current terms, APR, eligibility and any lender requirement in writing with the builder or lender before you rely on them.
Property tax figures are the county and city rates published for the year shown and are for planning only. Your actual bill depends on the assessed value, any exemptions and the city or district the home sits in. Confirm with the county assessor or trustee and your tax professional before you rely on a number.
DM me, text me or call 615-392-1186 and I'll show you how your home stacks up against the builders before you list.
Check out this article next