
Quick answer: A first-time buyer in Spring Hill, TN should settle three things before shopping: which county side (Williamson or Maury), which loan, and new construction or resale. The county changes your property tax rate and school district. THDA's Great Choice program works in both counties with a $500,000 purchase price limit and down payment help. And some Spring Hill homes for sale carry an FHA or VA loan you can take over at the seller's rate.
Here's a first-time buyer mistake I see a lot in Spring Hill.
You find a house you love. You run the payment on a mortgage calculator. You never ask which county it's in.
Spring Hill sits in two counties, Williamson and Maury, and the line runs right through town. Take two Spring Hill houses the county appraises at $400,000 each. Using the 2025 tax rates, the one on the Williamson side carries a county and city tax bill of about $2,009 a year. The one on the Maury side runs about $2,649. Same city, same appraised value, about $640 a year apart.
That's not a reason to pick one side. It's a reason to know before you fall in love.
I live next door in Thompson's Station and I sell in Spring Hill all the time. Here's how I'd walk you through your first purchase here, in the order I'd do it.
What a first purchase in Spring Hill looks like in 2026
Let's start with price, because everything else hangs on it.
The cleanest public numbers I can give you are what the builders are publishing for their new construction. Here's what they showed in October 2026:
| Community | County side | Builder | Builder-published price (date checked) |
|---|---|---|---|
| Barton Hills | Maury | Century Communities | homes at $389,990 to $459,990 (Oct 12, 2026) |
| Arbor Valley | Maury | Goodall Homes | "upper $400s" (Oct 5, 2026) |
| Harvest Point | Maury | D.R. Horton | from $489,990 (Oct 12, 2026) |
| August Park | Williamson | Richmond American | from $799,990 (Oct 5, 2026) |
| August Park | Williamson | Toll Brothers | from $829,995 (Oct 6, 2026) |
Builders change prices often, sometimes weekly. Treat this as a snapshot, not a quote.
Resale homes are the rest of the market, and they cover a wider range on both sides of the line. In September 2026, the median single-family sale price in Spring Hill was $662,500 on the Williamson side and $502,000 on the Maury side. For a first purchase, condos and townhomes are the lower entry point: their median that month was $239,372 on the Williamson side and $462,740 on the Maury side, both on very few sales, so take those two as a marker, not a promise.
Based on information from Realtracs® for the period September 1, 2025 through September 30, 2026.
One number to keep in your head: $500,000. That's THDA's purchase price limit for its Great Choice loans in both Williamson and Maury County. In October 2026, most of the new construction under that line was on the Maury side, with townhome communities like Preston Park the exception on the Williamson side. More on THDA below.
The county question
If you read one other page before you shop, make it what county Spring Hill, TN is in. Here's the short version for a first-time buyer.
Property taxes. Spring Hill charges its own city tax, and it's the same on both sides: $0.739 per $100 of assessed value. The county rate is what changes. For 2025, the Tennessee Comptroller lists:
| Where the home sits | County rate | City rate | Combined, per $100 of assessed value |
|---|---|---|---|
| Spring Hill, Williamson side | $1.27 | $0.739 | $2.009 |
| Spring Hill, Maury side | $1.91 | $0.739 | $2.649 |
Tennessee assesses a home at 25% of its appraised value. So a $400,000 appraisal is $100,000 assessed, which gives you the $2,009 and $2,649 from the top of this page. On a monthly payment, that gap is about $53.
Two things first-timers don't expect. A home inside Spring Hill gets two tax bills, one from the city and one from the county trustee. And Maury County is in a 2026 reappraisal year, so values and the county rate there will reset. Use the 2025 numbers to understand the gap, then pull the current bill on any house you're serious about.
School district. The county decides it. Williamson side homes are in Williamson County Schools, and Maury side homes are in Maury County Public Schools. Zones change street by street inside each district, so I pull the zoning for the exact address before you write an offer.
The ZIP doesn't tell you. 37174 covers both counties. Run the address through the U.S. Census geocoder and it'll name the county.
Loan options, in the order I'd price them
Don't pick a loan first and a house second. Get quotes on more than one, side by side, for the same price. Here's the order I'd have a lender run them.
1. Conventional. The baseline. A conventional loan doesn't require 20% down. With less down, you'll pay mortgage insurance until you build enough equity. If your credit is strong, this can be the cheapest loan over time. Ask your lender for their lowest down payment conventional option and price it first.
2. FHA. FHA lets you put down as little as 3.5%. The trade is FHA mortgage insurance, so compare the full monthly payment, not just the rate.
3. VA, if you're eligible. If you've served, price this one before you decide anything. The VA says there's no down payment as long as the price isn't higher than the appraised value, and no private mortgage insurance. There's a funding fee (2.15% on first use with less than 5% down, as of the VA's October 2026 page) unless you're exempt, for example if you receive VA disability compensation. I'm a Coast Guard veteran, so I'll admit this one's close to my heart.
4. THDA Great Choice. This is Tennessee's own program, run by the Tennessee Housing Development Agency. It isn't a separate kind of loan so much as a program layered on FHA, VA, USDA or a conventional HFA Advantage loan, with a 30-year fixed rate. Here's what matters in Spring Hill:
- Purchase price limit: $500,000 in both Williamson and Maury County, as of October 2026.
- Household income limits (THDA chart dated August 1, 2026): Williamson County, $139,320 for a 1 to 2 person household and $162,540 for 3 or more. Maury County, $124,320 and $145,040.
- Credit score: at least 640 for everyone on the loan.
- Down payment help, Great Choice Plus: a forgivable 0% second mortgage of up to $6,000 or up to $10,000, forgiven after 10 years; or an amortizing second of up to 5% of the price, capped at $15,000; or, on newly built homes, an amortizing second of up to $25,000 at 0% over 15 years.
- Homebuyer education class: required for the down payment help.
- First-time buyer rule: THDA waives it statewide for qualified military and veterans through Homeownership for Heroes, and in some Maury County census tracts it's waived too. Confirm the definition with the lender.
5. An assumption, the sleeper. Some homes for sale in Spring Hill carry the seller's FHA or VA loan at a rate far below today's, and you can take that loan over. You still have to qualify, and you have to cover the gap between the loan balance and the price. Here's a twist worth knowing: some of those FHA loans were made through THDA, and to assume one of those you have to meet THDA's rules, including being a first-time homebuyer. That's you. I explain it all in assumable mortgages in Spring Hill.
What we cover when we sit down
Before you tour a single house, we sit down for a buyer consultation. It's free, and it's where most of the expensive mistakes get prevented. Here's how it goes:
- What's going on in the market. I'll show you what's happening right now and whether you're walking into a buyer's market or a seller's market on the side of the county line you're looking at, because that changes how we write an offer.
- A little about me. Who I am, how I work and what you can expect from me.
- The whole process, start to finish. This is the main event. I walk you from this meeting to the keys in your hand: pre-approval, the search, the offer, inspection, appraisal, final walkthrough and closing, so nothing surprises you.
- The what-ifs. Can you back out of the deal, and when? What happens if the appraisal comes in low? What if the inspection turns something up? I'll show you the options you have at each of those points before you're standing in one of them.
- A lender in the room. If you want, I'll have a lender join us to see whether you qualify for first-time buyer programs or grant money, and to pin down the price range that fits your budget, not just what you could be approved for.
You'll leave knowing your number, your loan options and how the next few months will go. That's the point.
New construction vs resale in Spring Hill
Spring Hill has a lot of both, and a first-time buyer should look at both before deciding.
New construction. Builders here run incentives, and they change constantly. In October 2026 they ranged from straight price cuts to rate buydowns and closing cost money. D.R. Horton, for example, was running a "Red Tag" price event at Harvest Point from October 9 to November 1, 2026. Most of the rate and closing cost offers I track come with a condition: you have to use the builder's own lender. Sometimes that's a great deal. Sometimes a lender of your choosing beats it. You won't know until you price both.
Two more things. The sales office works for the builder, not for you, so bring me to your first visit and I'll be there to compare the incentive against nearby resale homes and check the zoning on your exact lot. And THDA's newly built option, up to $25,000 in down payment help, only applies to new construction, so if you qualify, that changes the math.
Resale. A resale home is finished. The landscaping has had time to grow in, and what you see is what you get. Sellers can pay toward your closing costs too, and some resale homes come with an assumable loan that no new house can offer. The trade is age: you'll want a good inspection and a clear read on the roof, HVAC and water heater.
For the neighborhoods behind those builder names, my best neighborhoods in Spring Hill breakdown sorts them by county side. And for everything else about the city, start with my Spring Hill area guide.
Your first step
Buying your first home doesn't have to feel like a test you didn't study for. Pick a county side, price your loan three ways, and look at new and resale before you decide.
Text or call me at 615-392-1186. Tell me your price range and when you want to move, and we'll set up your buyer consultation.
Text or call 615-392-1186.
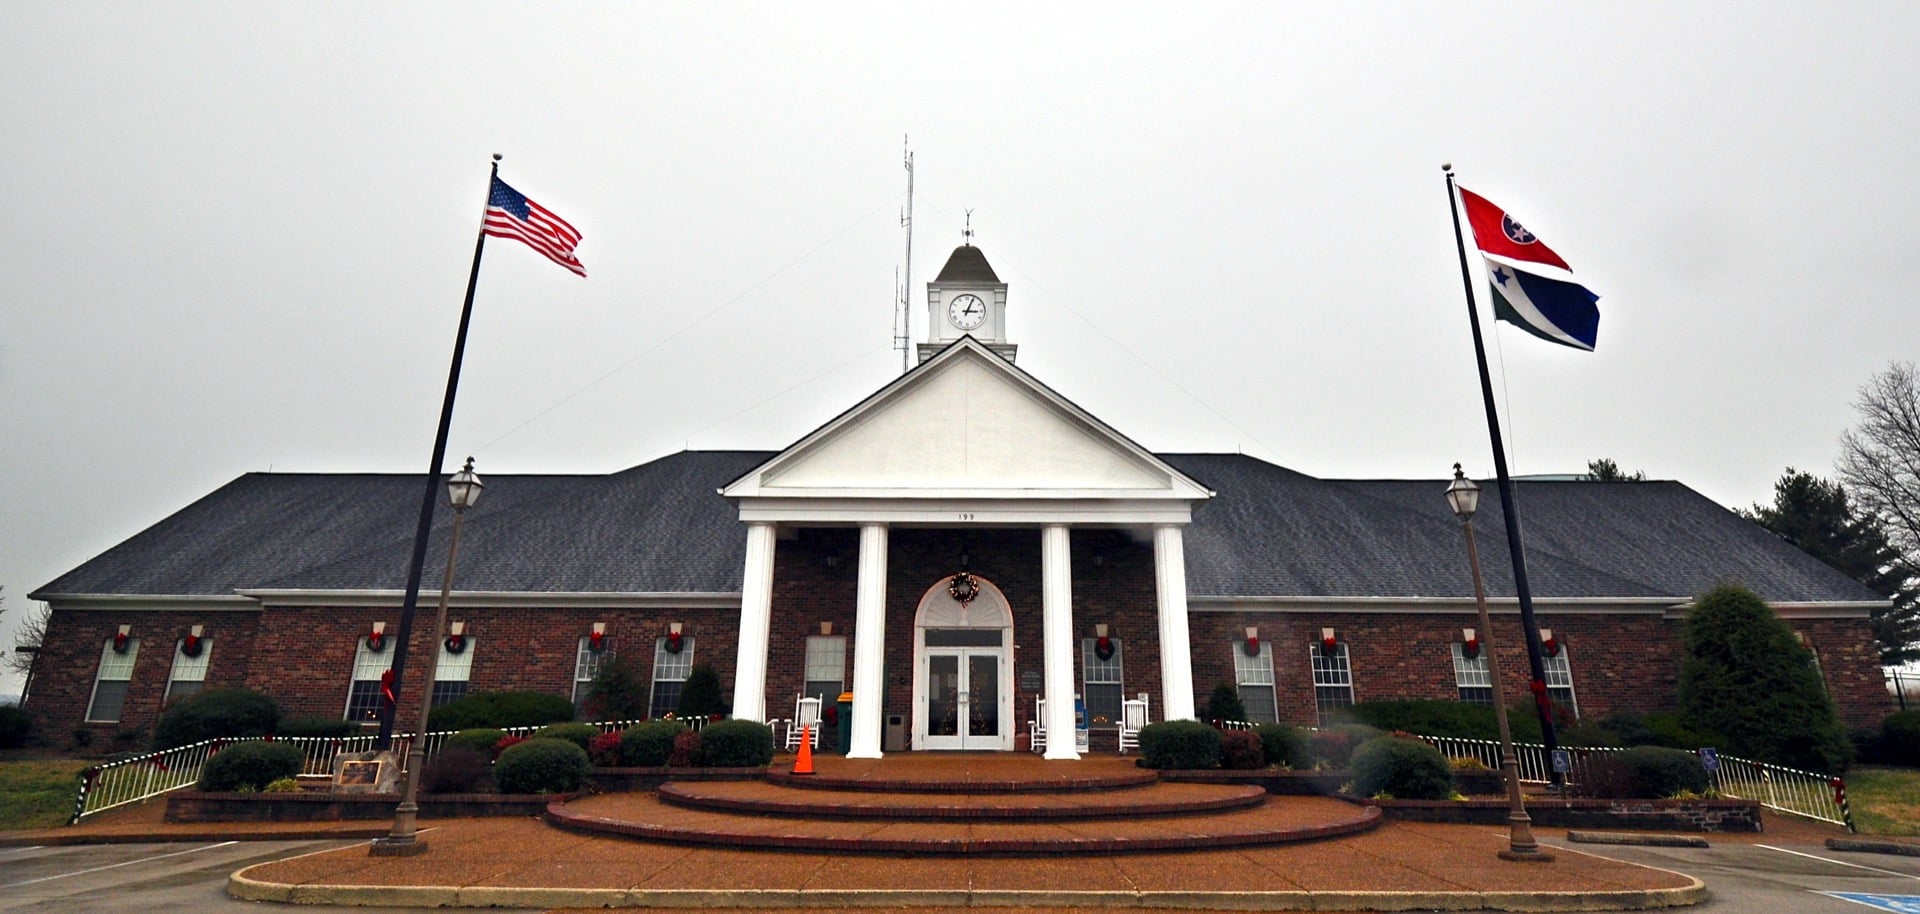
Photo: Spring Hill City Hall, by Skye Marthaler, CC BY-SA 3.0, via Wikimedia Commons.
First-time buyer questions
Does the county matter when buying a first home in Spring Hill, TN?
Yes. Spring Hill is in Williamson and Maury County. The county sets your school district and your county tax rate. For 2025, the combined city and county rate is $2.009 per $100 of assessed value on the Williamson side and $2.649 on the Maury side, per the Tennessee Comptroller.
Can I use THDA Great Choice in Spring Hill, TN?
Yes. THDA's Great Choice program works in both Williamson and Maury County, with a $500,000 purchase price limit in each. Income limits differ by county and household size, the minimum credit score is 640, and a homebuyer education class is required for down payment help.
How much down payment does a first-time buyer need in Spring Hill?
It depends on the loan. FHA allows as little as 3.5% down. VA loans need no down payment if the price isn't above the appraised value. Conventional loans don't require 20%. THDA's Great Choice Plus can help with the down payment and closing costs.
Can a first-time buyer assume a mortgage in Spring Hill?
Yes. Some Spring Hill homes for sale have FHA or VA loans the buyer can take over at the seller's rate. You have to qualify with the loan servicer and cover the gap between the loan balance and the price. Assuming a THDA-financed FHA loan also requires meeting THDA's first-time buyer rules.
Do Spring Hill builders offer incentives to first-time buyers?
Builders in Spring Hill run incentives that change often, from price cuts to rate buydowns and closing cost help. Many rate and closing cost offers require using the builder's own lender. Compare the incentive against a lender of your choosing and against nearby resale homes.
Is new construction or resale better for a first home in Spring Hill?
Neither is better for everyone. New construction comes with builder incentives and THDA's newly built down payment option of up to $25,000. Resale homes are finished, can come with seller-paid closing costs, and some have an assumable loan. Price both before you decide.
Check out this article next